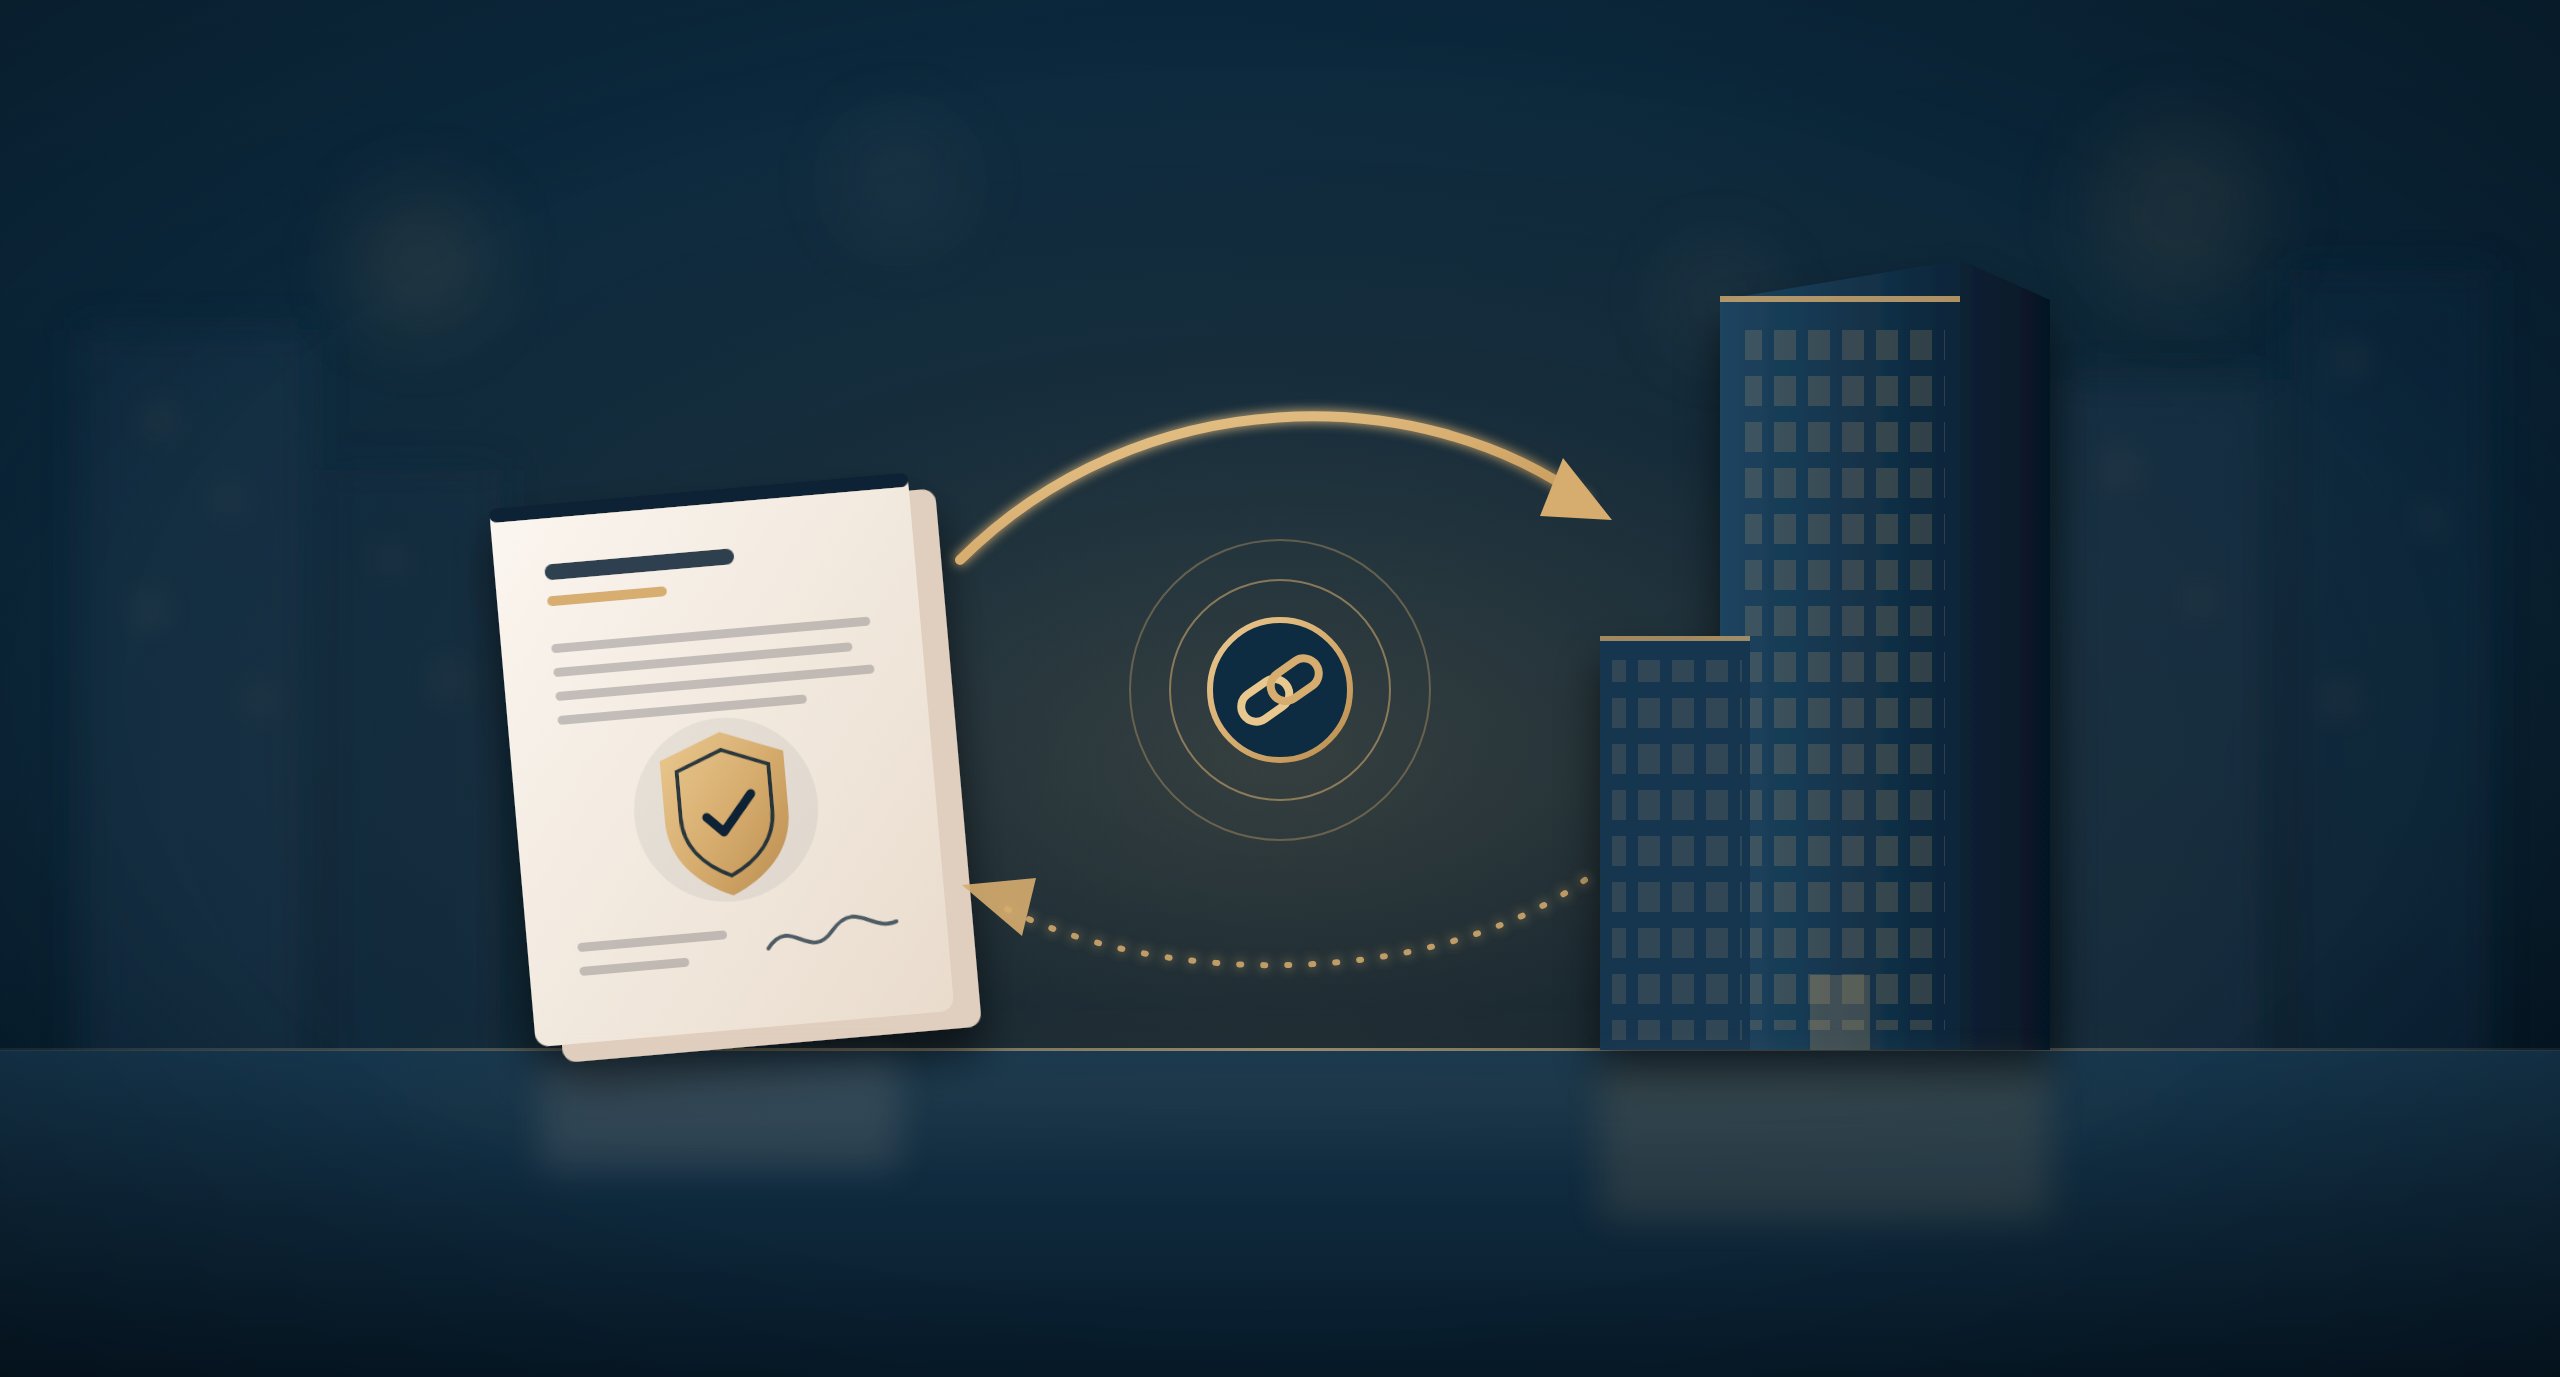
An Immediate Financing Arrangement (IFA) lets a Canadian corporation pledge permanent life insurance and borrow against it, up to cash value or, with some lenders, the full premium, to reinvest. Loan interest and part of the premium may be deductible. At death, proceeds repay the loan; the death benefit less adjusted cost basis is generally payable as tax-free capital dividends.
By Carl Brodie, CFP® professional · Last updated: November 22, 2026.
Rates, lender terms and figures on this page are stated “as of Q4 2026” and are reviewed quarterly.
An Immediate Financing Arrangement (IFA) combines a life insurance policy, a bank loan and a set of tax rules, and each part carries its own risk. This guide answers the questions Canadian business owners ask most, briefly, and links to deeper guides on each.
In This Guide
What is an Immediate Financing Arrangement and how does it work?
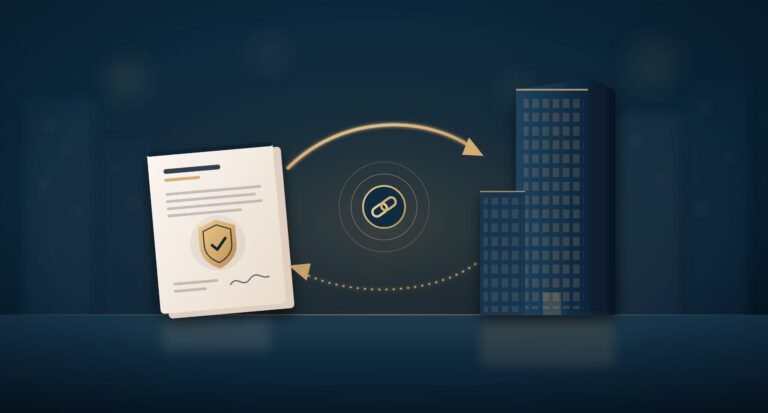
An Immediate Financing Arrangement (IFA) is a structure in which a Canadian corporation owns a permanent life insurance policy, usually participating whole life, assigns that policy to a lender, and borrows against it so that the premium dollars go back to work in the business or in income-earning investments. The corporation keeps its working capital, and the policy builds cash value and a death benefit in the background.
In practice, the arrangement usually follows these steps:
- Planning and underwriting. The corporation, its accountant and an advisor confirm a lasting need for permanent coverage and an income-earning use for the borrowed funds. The insured person goes through underwriting.
- Policy issue. The Canadian corporation owns a life insurance policy, usually participating whole life, and pays the premiums from its own funds.
- Assignment. The corporation assigns the policy to the lender as collateral for a loan or line of credit.
- Advance. The lender advances funds tied to the premium paid and the policy’s cash surrender value. Funding timelines vary by lender.
- Reinvestment. The corporation uses the borrowed funds in its business or in income-earning investments and keeps them traceable to that use, because the use decides whether the interest is deductible.
- Annual cycle. Each year the corporation pays the premium, the lender advances again, and the corporation pays the loan interest, usually monthly. Terms on capitalizing or re-borrowing interest vary by lender; confirm current terms with the lender.
- Exit. At the insured person’s death, the death benefit repays the loan and the rest stays in the corporation. The CDA credit is generally the full death benefit less the policy’s adjusted cost basis, including the part used to repay the loan (CRA Folio S3-F2-C1, paragraph 1.67).
Who is an IFA for?
An Immediate Financing Arrangement (IFA) is usually considered by owners of a profitable Canadian corporation who intend to hold permanent life insurance and would otherwise take capital out of the business to pay for it. The typical profile:
- Steady, predictable corporate cash flow.
- A lasting need for permanent coverage: estate liquidity, a buy-sell arrangement, or capital the family will need at death.
- An income-earning use for the borrowed funds, in the business or an investment portfolio.
- A horizon measured in decades, insurable health, and an accountant involved from the start.
Who lends for IFAs in Canada, and what rates do they charge?
An Immediate Financing Arrangement (IFA) in Canada is financed by a lender that accepts an assignment of the policy as collateral, usually one with a specialized insurance lending program, though a client’s own bank can also lend. Terms differ by lender and change over time.
The type of lender matters for tax as well as pricing. The collateral insurance deduction in paragraph 20(1)(e.2) of the Income Tax Act applies only where the policy is assigned to a “restricted financial institution” in the course of a borrowing, and the lender requires the assignment as collateral (ITA 20(1)(e.2)). A restricted financial institution includes a bank, trust company, credit union, insurer or a lender whose principal business is lending at arm’s length (ITA 248(1)).
What we’ve seen lately (Q4 2026)
These are the ranges we have seen in recent Stone Owl cases. They are not an offer, a quote or a guarantee. Stone Owl does not lend or set rates.
- Loan-to-value: from 90% of cash value up to 100% of the premium, depending on debt servicing, credit profile and whether the client offers additional collateral.
- Interest rates: from the lender’s prime rate minus 0.35% to prime plus 2%, usually floating, depending on the lender, loan size and the client’s credit profile.
- Personal guarantees: often required, but not always.
- Structure: Some lenders require the policy to be owned by a holding company, and the loan can then go to the holding company or to the owner personally.
General information only, not an offer of credit and not tax, legal or lending advice. Terms vary by lender and borrower and change over time.
When you compare lenders, the rate is only one line. Ask how the rate is set and how often it can change, whether interest must be paid each year or can be added to the loan, what happens if the collateral value falls short, and what a personal guarantee would cover.
How much can you borrow, and is the policy enough collateral?
An Immediate Financing Arrangement (IFA) loan is limited to a share of the policy’s cash surrender value set by the lender. Lenders typically advance up to most or all of a policy’s cash value, and some require extra collateral; terms vary by lender and change over time. BMO’s description as of 2026-02-03 puts its margins at 90% to 100% of cash surrender value for whole life, lower for some universal life accounts. Some lenders advance up to the full premium (RBC Wealth Management, undated), and BMO’s description says up to 100% of deposits.
In the early years the cash value can be lower than the loan, so lenders may require additional collateral or limit the advance to the cash value; BMO’s description as of 2026-02-03 says additional security is normally released once the CSV covers the loan. Some lenders also ask for a guarantee; terms vary by lender. IFA loans are often demand loans or lines of credit the lender can call (BMO’s description as of 2026-02-03), so if the cash value grows more slowly or rates rise, a lender may ask for more collateral or a paydown.
Why do lenders want a personal guarantee, and what's the guarantee fee?
An Immediate Financing Arrangement (IFA) lender may ask the shareholder to guarantee the corporation’s loan personally. When a guarantee is required, and what it covers, varies by lender and isn’t generally published; some lenders list guarantors among required documents (BMO’s description as of 2026-02-03). If the corporation pays the shareholder a fee for the guarantee, there is no standard rate: the fee should be reasonable, generally what an arm’s-length guarantor would charge, and that is a question of fact. The fee is income to the shareholder, reported on a T4A, and the corporation can generally deduct a reasonable fee when the loan is used to earn income (ITA 20(1)(e) and (e.1)).
What's tax-deductible in an IFA?
An Immediate Financing Arrangement (IFA) can produce two deductions for a Canadian corporation, and neither is automatic:
- Loan interest, ITA 20(1)(c). Deductible when the borrowed money is used to earn income from a business or property. Money borrowed to acquire a life insurance policy does not qualify, so the premiums come from the corporation’s own funds and the loan proceeds are kept traceable to their income-earning use (ITA 20(1)(c); CRA Folio S3-F6-C1, effective August 8, 2024). Interest added to the loan instead of paid changes when it can be deducted (ITA 20(1)(d)). Interest on money borrowed to pay deductible interest is itself generally deductible; interest simply added to the loan is deductible only when paid (S3-F6-C1 ¶1.81 to 1.83).
- Part of the premium, ITA 20(1)(e.2). Available only where the policy is assigned to a restricted financial institution that requires it as collateral, the loan interest is deductible, and the borrower is the policyholder. The deduction is the least of the premium, the policy’s net cost of pure insurance, and the part of the lower of those two that relates to the loan balance, usually a modest fraction of the premium (ITA 20(1)(e.2); archived IT-309R2).
Both depend on the structure staying clean: a standard IFA, where the bank loan and the policy are independent, is not a “10/8 policy” (which loses these deductions and the CDA credit for the loan), and the policy must remain an “exempt policy” for its cash value to grow tax-deferred.
What happens when the insured person dies?
An Immediate Financing Arrangement (IFA) ends, in most cases, when the insured person dies: the death benefit repays the loan. Terms vary by lender and change over time; confirm current terms with the lender.
The private corporation’s capital dividend account (CDA) is credited with the life insurance proceeds less the policy’s adjusted cost basis (ITA 89(1)). Where the policy was only collaterally assigned, CRA treats the full proceeds as received by the corporation, including the part paid to the lender, so the loan repayment does not reduce the credit unless the policy is a “10/8 policy” (S3-F2-C1, paragraphs 1.60.2 and 1.66 to 1.67, effective January 13, 2025). The corporation can then pay a capital dividend up to that balance tax-free, on two conditions: it files the subsection 83(2) election by the time the dividend is paid or becomes payable, and the dividend goes to Canadian-resident shareholders (ITA 83(2); S3-F2-C1, paragraph 1.2). A dividend above the CDA balance triggers an additional tax.
A simplified illustration, not a projection. A $2,000,000 death benefit on a policy with a $300,000 adjusted cost basis creates a $1,700,000 CDA credit. Paying the full capital dividend still requires the corporation to have the cash or other assets after the loan is repaid. The figures are hypothetical.
What are the risks, and how do you stress test an IFA?
An Immediate Financing Arrangement (IFA) carries three main risks: interest rates can rise, the insurer’s dividend scale can fall, and the corporation’s cash flow can change. We test them before anything is signed by modelling three scenarios:
- Base case: current lender rate and current dividend scale.
- Rates up 2%: the loan rate is two percentage points higher for the life of the plan.
- Dividend scale down 1%: the dividend scale interest rate is one percentage point lower than illustrated.
For each we look at cumulative net interest (interest paid less the tax value of the deductions) and the break-even year.
Other risks worth naming plainly:
- Collateral calls. If the loan outgrows the collateral, or policy values come in below the illustration, the lender may limit advances or ask for more security, current interest or a paydown.
- Tax law and anti-avoidance. The rules described here can change, and CRA can challenge an arrangement under the general anti-avoidance rule (section 245), strengthened in June 2024 with an economic-substance test and penalties. The mandatory disclosure rules should also be reviewed.
- Commitment and underwriting. Premiums are expected for many years, stopping early can be costly, and a change in health before issue can change the terms.
Related reading: What are the risks of an Immediate Financing Arrangement?
What if you sell the company, wind it up, or can't keep up the deposits?
An Immediate Financing Arrangement (IFA) is built for the long term, so a sale, a wind-up or a cash squeeze should be planned for at the start. Moving the policy to another company, surrendering it, or taking withdrawals or policy loans from the insurer are dispositions that can create a taxable policy gain, and the cash left after the lender is repaid may not cover that tax (ITA 148).
If the loan grows past the lender’s margin (for example, because deposits stop, cash value grows more slowly or rates rise), terms vary by lender and change over time; confirm current terms with the lender. Policy-side options such as reduced paid-up coverage, where coverage is reduced so premiums stop (Canada Life, “Waiver of premiums”, undated), have lasting consequences, and borrowing later for retirement income depends on the lender and the margin, so confirm both with your insurer and lender before acting.
Do participating policies actually perform like the illustration?
An Immediate Financing Arrangement (IFA) most often uses participating whole life, and the illustration you are shown is not a forecast. Illustrations are built on the insurer’s current dividend scale, which is not guaranteed and is reviewed by the insurer over time. Actual results may be higher or lower than illustrated.
Ask any advisor for the illustration at a lower dividend scale, the insurer’s dividend scale history, and which values are guaranteed.
IFA vs the alternatives
An Immediate Financing Arrangement (IFA) is one of several ways a Canadian corporation can use retained earnings, and for many owners a simpler option fits better.
Immediate Financing Arrangement (IFA)
- Liquidity
- Capital stays in the business through the loan; policy is pledged to the lender
- Tax treatment
- Interest may be deductible if funds earn income; part of premium may be deductible; death proceeds less ACB credited to the CDA
- Risk
- Rate, dividend scale, collateral and long-term commitment risk
- Who it fits
- Profitable corporation, long horizon, permanent coverage need, stable cash flow
Invest inside the corporation
- Liquidity
- High, depending on investments
- Tax treatment
- Passive investment income is taxed in the corporation at high rates. Adjusted aggregate investment income over $50,000 a year reduces the small business limit by $5 for every $1, eliminating it at $150,000 (ITA 125(5.1)(b))
- Risk
- Market risk
- Who it fits
- Owners who want flexibility and no long-term premium commitment
Pay down debt
- Liquidity
- Reduces available capital; frees future cash flow
- Tax treatment
- No deduction for principal repaid
- Risk
- Low
- Who it fits
- Owners carrying higher-cost or non-deductible debt
Buy insurance without leverage
- Liquidity
- Premiums leave the business
- Tax treatment
- Premiums generally not deductible; death proceeds less ACB credited to the CDA
- Risk
- Lower; no loan or collateral calls
- Who it fits
- Owners with a coverage need who prefer no borrowing
“Infinite banking”
- Liquidity
- Policy loans or withdrawals from cash value
- Tax treatment
- Usually a personal policy; policy loan interest is deductible only for an income-earning use with Form T2210, and a policy loan can create a taxable gain (S3-F6-C1, paragraph 1.84)
- Risk
- Policy performance and loan risk
- Who it fits
- Not the same strategy as an IFA
For the broader tax picture, see Using Life Insurance to Reduce Tax in Canada.
What most business owners miss about an IFA
An Immediate Financing Arrangement (IFA) is usually presented as a tax strategy, but the result depends more on the borrowed money and the loan than on the policy:
- The use of the loan decides the interest deduction. If it funds personal spending or the premiums, the deduction is at risk.
- The collateral deduction depends on the lender. It requires an assignment to a restricted financial institution that requires it as collateral.
- The CDA credit and the cash are different numbers. The loan repayment does not reduce the credit, so the credit can exceed the cash left.
- Collateral risk depends on the lender’s margin. Terms vary by lender and change over time; confirm current terms with the lender.
Risks and who this isn't for
An Immediate Financing Arrangement (IFA) is not suitable for every Canadian corporation, and we would rather say so plainly than adjust the numbers until they appear to work. In our view an IFA is usually not the right fit if any of the following applies:
- Cash flow is uneven or uncertain. The structure assumes premiums and interest can be paid every year.
- There is no lasting need for permanent coverage. If insurance is not needed for the long term, the cost of the policy is hard to justify.
- The time horizon is short. A plan to sell, wind up or retire within a few years leaves little time for the structure to work.
- Variable rates are uncomfortable. IFA loans are typically variable-rate lines of credit, so borrowing costs can change with interest rates.
- Health makes insurance expensive. Higher underwriting ratings can make the cost of coverage outweigh the benefit.
- There is no productive use for the borrowed money. Without an income-earning use, the interest deduction may not be available.
If one of these describes your situation, a simpler option from the comparison above may serve you better, and we will say so.
FAQs About Immediate Financing Arrangements (IFA)
An Immediate Financing Arrangement (IFA) raises many of the same questions each time. These short answers reflect the wording business owners and their accountants use with us.
Who lends for an IFA in Canada?
An Immediate Financing Arrangement (IFA) loan in Canada comes from a lender that accepts an assignment of the life insurance policy as collateral. For the collateral insurance deduction under ITA 20(1)(e.2), the policy must be assigned to a restricted financial institution. Lender terms differ and change, so compare dated term sheets.
What does the interest on an IFA really cost?
The real cost of Immediate Financing Arrangement (IFA) interest is the interest paid less the tax value of any deduction. Interest is deductible under ITA 20(1)(c) only if the borrowed money is used to earn income from a business or property, and the interest must be reasonable (S3-F6-C1, Summary). We model cumulative net interest under several rate scenarios before anything is signed.
Do I have to pay the IFA interest personally, or does it keep growing?
In an Immediate Financing Arrangement (IFA), the corporation is normally the borrower and pays the interest. Lenders typically require interest to be paid monthly. Terms on capitalizing or re-borrowing interest vary by lender; confirm current terms with the lender.
When does IFA interest stop being deductible?
Immediate Financing Arrangement (IFA) interest can stop being deductible if the borrowed money is no longer used to earn income from a business or property, or if it is used to acquire the life insurance policy itself. The current use of the funds is what matters, for example, if the investments bought with the loan are sold and the proceeds are not reinvested to earn income (S3-F6-C1, paragraphs 1.35 to 1.37). Your accountant should review this every year.
Can I cancel an IFA at any time?
An Immediate Financing Arrangement (IFA) can be unwound, but the loan must be repaid or refinanced first, and surrendering the policy may create taxable income and end the coverage. Stopping early is often costly, which is why we plan exit options before the policy is issued.
What happens to the IFA loan when the insured person dies?
When the insured person dies, the death benefit repays the Immediate Financing Arrangement (IFA) loan. The corporation keeps the rest, and its capital dividend account is generally credited with the full proceeds, including the part that repaid the loan, less the policy’s adjusted cost basis (ITA 89(1); CRA Folio S3-F2-C1).
Why is the CDA payout tax-free to shareholders?
A capital dividend paid from an Immediate Financing Arrangement (IFA) death benefit is tax-free to Canadian-resident shareholders because, when the private corporation files the election under ITA 83(2), no part of the dividend is included in the shareholder’s income. The dividend is limited to the private corporation’s capital dividend account balance.
Is an IFA the same as infinite banking?
No. An Immediate Financing Arrangement (IFA) is a corporate structure in which a Canadian corporation borrows from a lender against a policy it owns and uses the funds to earn income. “Infinite banking” usually describes borrowing against a personally owned policy, and the tax treatment is different.
Conclusion: an IFA is a long-term structure, not a product
An Immediate Financing Arrangement (IFA) can be a sensible way for a Canadian corporation to hold permanent life insurance without drawing down its working capital. It works when the coverage need is real, cash flow is steady, the borrowed money earns income, and the structure has been tested against higher rates and lower dividends. It is not the right answer for every owner.
We look at the lender, the insurer, the tax rules and the exit with you and your accountant, and if a simpler path suits your corporation better, we will tell you.
If you would like to talk through how a stress test would read for your own corporation, you can book a discovery call.
Book a discovery call
This article is general information about Canadian tax and insurance rules as of Q4 2026 and is not tax, legal or investment advice. Tax treatment depends on your circumstances and on current law, which can change. Policy values that are not guaranteed may be higher or lower than illustrated. Speak with your accountant and advisor before acting. This is not an offer of credit or a recommendation to buy any product. Leverage magnifies losses as well as gains when the borrowed money is invested.
Stone Owl Financial Inc. receives commission from insurers on policies placed.
Stone Owl Family Office Inc. and Stone Owl Financial Inc. are separate corporate entities which are affiliated. Stone Owl Financial Inc. is a business segment of Stone Owl Family Office Inc. Stone Owl Financial Inc. is licensed in British Columbia, Alberta and Ontario. Contracted by HUB Financial Inc, as the Managing General Agent.
Sources
We link legislation, CRA publications, and lenders’ and insurers’ own public materials.
- Government of Canada (Justice Laws), Income Tax Act, section 20
- Government of Canada (Justice Laws), Income Tax Act, subsection 83(2) and subsection 89(1)
- Government of Canada (Justice Laws), Income Tax Act, paragraph 125(5.1)(b), section 148, section 245 and subsection 248(1)
- Canada Revenue Agency, archived Interpretation Bulletin IT-309R2, Premiums on Life Insurance Used as Collateral
- Canada Revenue Agency, Income Tax Folio S3-F6-C1, Interest Deductibility
- Canada Revenue Agency, Income Tax Folio S3-F2-C1, Capital Dividends
- BMO Insurance, Leveraged Life Insurance: An Overview of the BMO Private Banking program, form 947E
- Canada Life, “Waiver of premiums: protecting your participating life insurance policy”
- RBC Wealth Management, “How high-net-worth Canadians are turning credit into wealth”
Lenders and insurers are named only to identify the source of public information. No partnership, recommendation or endorsement is implied.

What do you think?
[…] Borrowing against the policy. Some corporations assign a policy to a lender and reinvest the borrowed money; this is the basis of an Immediate Financing Arrangement, which carries its own risks. See Immediate Financing Arrangements in Canada: The Complete Guide. […]